
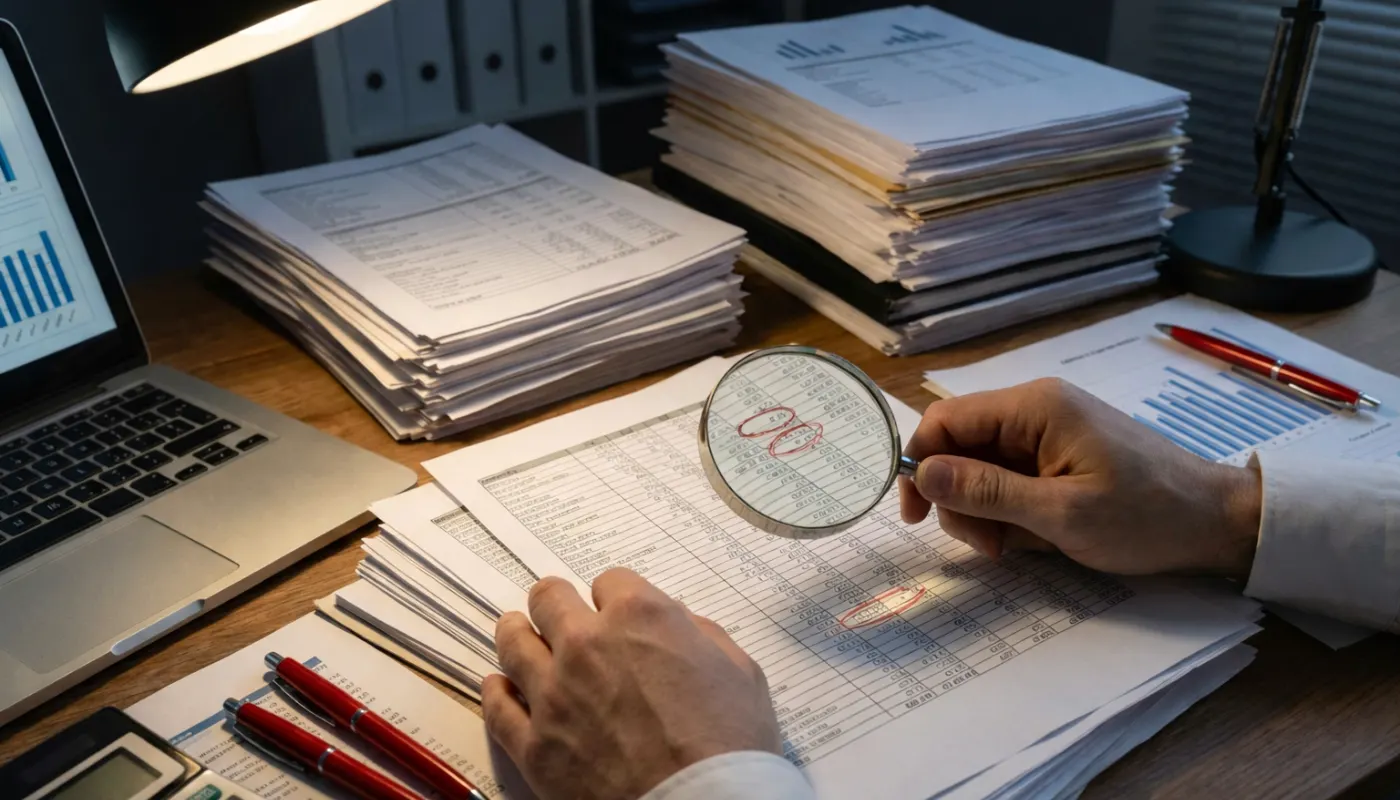
Fraud allegations can involve years of transactions, emails, contracts, account entries, and decisions made by several people. A quick verbal explanation rarely captures that complexity. Before responding formally, preserve original financial material, identify who controlled each transaction, and build a timeline showing what records existed when important decisions were made.
Identify the Transaction at the Center of the Allegation
Start by determining which payment, representation, application, contract, reimbursement, or transfer is actually being questioned. Fraud is a broad label, while criminal statutes contain specific elements that vary by offense and jurisdiction.
The U.S. Department of Justice investigates and prosecutes multiple forms of federal fraud, including schemes involving government programs, investors, consumers, and financial markets. A state fraud case may operate under different statutes and procedures.
Build a Complete Financial Record
Gather bank statements, invoices, payment confirmations, loan documents, contracts, accounting entries, and correspondence. Keep entire records rather than selecting only pages that appear favorable.
If the allegation intersects with insolvency or unpaid obligations, broader bankruptcy law information may provide general context. Financial distress alone, however, does not establish that a particular representation or transaction was fraudulent.
| Document | Question It May Address | Preserve |
|---|---|---|
| Bank statement | Where money moved | Full statement |
| Contract | Agreed duties | Signed version |
| Email thread | What was represented | Complete chain |
| Ledger | How transaction was recorded | Original export |
Determine Who Had Authority to Act
Business fraud cases often involve several employees, executives, accountants, vendors, or owners. Titles do not always reveal who approved a payment or who supplied information used in a filing.
Corporate records can help clarify responsibilities. General corporate legal resources may provide background terminology, while the case itself may require organizational charts, board records, approval logs, contracts, and account-access histories.
Preserve Tax Materials Without Reconstructing Them
Tax filings, payroll records, deductions, business returns, and communications with tax professionals can become relevant when investigators are examining financial statements or representations.
Reviewing general tax law discussions is different from obtaining advice about a criminal investigation. Do not backdate documents, recreate missing invoices as though they were originals, or change accounting descriptions after learning that records are under scrutiny.
Where Informal Explanations Can Go Wrong
Complex transactions are difficult to explain from memory. A person may give an incorrect number or date without intending to mislead, yet the inconsistency can later become part of the investigative record.
Another risk is selectively producing documents without understanding the request. Preserve the full set first. Counsel can then evaluate subpoenas, warrants, interview requests, production obligations, privileges, and deadlines under the applicable law.
When to Contact a Lawyer Quickly
Legal help is especially important after receiving a subpoena, search warrant, target letter, charging document, interview request, or demand for records from investigators. Businesses may also need to coordinate document preservation so employees do not automatically delete emails or files.
Federal criminal procedure provides mechanisms for charging, pretrial motions, counsel, trial, and sentencing, but the exact path depends on the case.
Frequently Asked Questions
Should I explain suspicious transactions to investigators immediately?
A rushed explanation can create inaccuracies in a document-heavy case. You can obtain legal advice before deciding how to respond to a voluntary interview request or how to address questions about complex transactions.
Can accounting errors automatically become criminal fraud?
An accounting mistake does not automatically establish criminal fraud. The specific statute, evidence, required mental state, representations made, and surrounding circumstances must be considered before criminal responsibility can be determined.
Should old business emails be preserved?
Potentially relevant emails should generally be kept intact once a dispute or investigation is known. Automatic deletion systems and routine document destruction may require prompt attention, particularly in organizations managing large volumes of electronic records.
Let the Documents Establish the Sequence
Fraud cases often become clearer when financial records are organized chronologically and linked to the people who created, approved, or received them. Preserve originals before offering broad explanations, identify missing records without inventing replacements, and obtain advice about formal demands. A careful record is more reliable than a hurried reconstruction.
This article is for general informational purposes and is not a substitute for legal advice from a qualified attorney.